Summary
Paying for assisted living without selling your house is possible through multiple financial strategies that help preserve this important asset. Families have several options to explore before considering a home sale.
- Access home equity through reverse mortgages, equity loans, or lines of credit without requiring you to move out
- Explore Medicaid benefits, which often don't require selling your primary residence and may exempt your home from asset calculations
- Investigate Veterans Aid and Attendance benefits if you're a wartime veteran or surviving spouse—benefits can provide hundreds to thousands monthly
- Consider unlocking life insurance through accelerated death benefits, life settlements, or policy loans
- Generate ongoing income by renting your home or securing a bridge loan while you explore longer-term financial solutions
Moving into assisted living doesn't always mean selling the family home. For many older adults, keeping the property provides emotional comfort, financial flexibility, or a place for loved ones to continue living.
Fortunately, several options may help with paying for assisted living without selling the house. From home equity and rental income to insurance and veterans benefits, understanding your choices can help you plan for care without rushing into a property sale.
Using Home Equity to Pay for Assisted Living
Your home's equity may provide access to funds while allowing you to retain ownership. However, each financing option comes with different requirements and potential risks.
Common options include:
- Reverse Mortgages: Available to eligible homeowners age 62 and older, these loans convert home equity into funds. However, the home generally must remain the borrower's primary residence. Moving permanently into assisted living may trigger repayment, making this option unsuitable for some families.
- Home Equity Loans: These provide a lump sum secured by your property. You'll typically make monthly payments while retaining ownership.
- Home Equity Lines of Credit (HELOCs): These allow eligible homeowners to borrow against their equity as needed, usually with variable interest rates.
Before borrowing, consider repayment obligations, interest charges, and how the arrangement could affect your long-term finances.
Medicaid Planning and Keeping Your House
Some families wonder whether they can keep a house while in assisted living and still qualify for Medicaid assistance.
In Wisconsin, Medicaid eligibility depends on financial circumstances, applicable program requirements, and the type of services needed. A primary residence may receive certain asset protections, particularly when an eligible spouse or dependent family member continues living there.
However, retaining property doesn't automatically guarantee eligibility or protect it from future estate recovery claims.
Understanding Wisconsin's Medicaid Requirements
Working with a Wisconsin elder law attorney can help families understand:
- Home equity limits and applicable asset exemptions
- Eligibility requirements for available Medicaid programs
- Potential estate recovery obligations
- How trusts or other financial arrangements may affect eligibility
Because Medicaid coverage for assisted living services varies, confirm both program eligibility and community participation before making financial decisions.
Veterans Benefits and Aid and Attendance
Veterans and eligible surviving spouses may qualify for VA Aid and Attendance benefits to help cover certain long-term care expenses.
This benefit provides additional monthly payments to qualifying individuals who need assistance with everyday tasks. Eligibility depends on military service, financial circumstances, and personal care needs.
At LakeHouse Manitowoc, the Military Veterans Program recognizes those who served and offers exclusive savings for eligible veterans.
Families can explore community savings alongside available VA benefits when considering assisted living payment options. Confirm eligibility and program details directly before including either in your budget.
Long-Term Care Insurance and Life Insurance Options
Existing insurance policies may offer another way to cover expenses while keeping your property.
Long-Term Care Insurance
Some long-term care insurance policies help pay for assisted living services, depending on coverage terms and eligibility.
Review your policy for benefit amounts, waiting periods, covered services, and claim requirements. Understanding these details early can help prevent unexpected expenses.
Life Insurance Options
Depending on your policy, potential funding sources include:
- Accelerated Death Benefits: Certain policies allow early access to benefits when specific medical criteria are met.
- Life Settlements: Eligible policyholders may sell their policies to third parties for an immediate payment.
- Policy Loans: Permanent life insurance policies with accumulated cash value may allow borrowing against that value.
Each option has financial consequences, including possible taxes, fees, or reduced benefits for beneficiaries. Consult a qualified advisor before proceeding.
Rental Income and Bridge Loans
Renting out your property may provide ongoing income to help cover assisted living expenses without selling it.
For homeowners comfortable managing tenants, or hiring a property manager, rental income can help offset monthly costs. Remember to account for maintenance, property taxes, insurance, and possible vacancies.
Bridge loans offer another approach to financing senior living without a home sale. These short-term loans may provide temporary funds while families arrange longer-term financing or access other assets.
However, repayment deadlines and interest costs make careful planning essential. This approach may be more appropriate when a reliable future source of repayment exists.
Creating a Financial Plan That Works for Your Family
Combining alternative ways to pay for senior care may provide greater flexibility than relying on one funding source.
Start by reviewing your income, savings, insurance benefits, and ongoing property expenses. Then compare those resources with the total cost of assisted living.
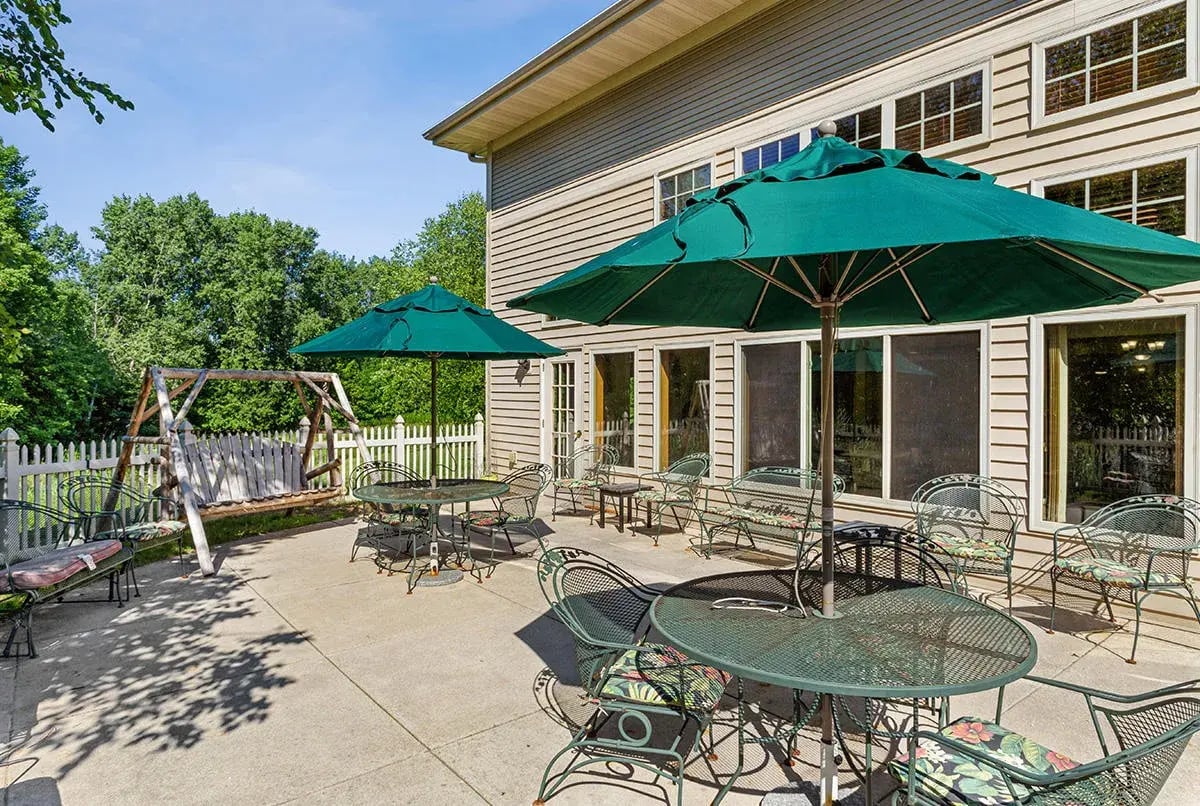
At LakeHouse Manitowoc in Manitowoc, WI, residents enjoy chef-prepared meals, weekly housekeeping, scheduled transportation, and comfortable private apartments with kitchenettes. These conveniences can simplify everyday life while providing personalized support.
Families can explore available floor plans and pricing to better understand their options.
Affording care without selling property often requires thoughtful planning and professional guidance. By evaluating available resources and understanding their limitations, families can make decisions that support both current needs and long-term financial goals.
Schedule a tour of LakeHouse Manitowoc today to explore Assisted Living, discuss available pricing, and discover a welcoming community where your loved one can feel at home.